Why Every Home With Solar Panels Needs Insurance
Think about it this way. You save up, you plan carefully, and you put solar panels on your roof. It feels good, right? Lower electricity bills, clean energy, and a sense that you’ve made a smart choice for your home.
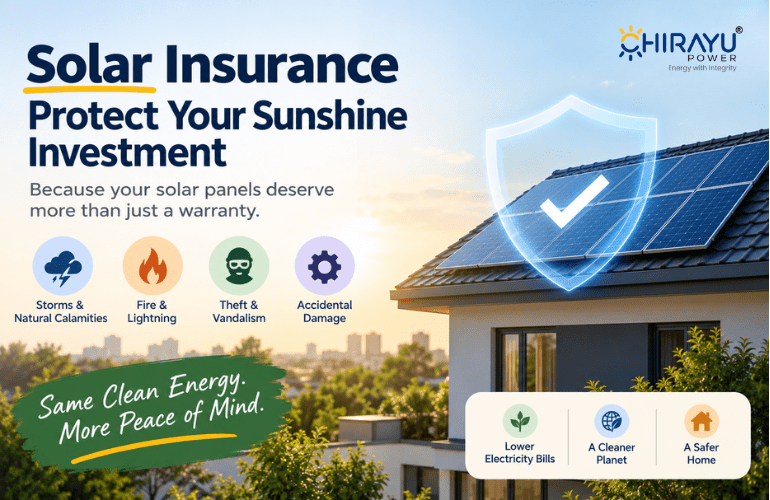
But here’s something most people don’t think about until it actually happens. What if a heavy storm blows off your panels? What if lightning strikes and damages your inverter? What if there’s a fire, a flood, or even a theft? Suddenly, that smart investment you made turns into a big, unplanned expense.
This is exactly why solar insurance matters so much. It’s not an extra cost you can skip; it’s a safety net for something you’ve spent real money on. A small yearly premium can save you from paying lakhs of rupees out of your own pocket if something goes wrong. No one can predict when bad weather or an accident will strike, so it’s worth taking a few minutes to protect the system that’s saving you money every month.
What Can Actually Go Wrong on an Indian Rooftop
A rooftop solar system sits outdoors for 25 years, through every monsoon, hailstorm, and heatwave. Some of that risk belongs to your warranty. Some belongs to insurance.
- Storms and cyclones – Coastal states like Gujarat, Odisha, West Bengal, and Tamil Nadu see winds strong enough to damage poorly anchored structures.
- Hailstorms – Common in Punjab, Haryana, and parts of Madhya Pradesh. A single cracked panel can affect an entire string’s output.
- Fire and lightning – Degraded DC connectors can cause fires, and lightning surges can destroy an inverter even when panels survive.
- Theft – Panels and copper cabling are common targets, especially on accessible rooftops or ground-mounted systems.
- Falling objects – Tree branches, water tank overflows, or construction debris.
- Inverter failure – The most common failure point, usually a warranty matter rather than insurance.
The first five are external events, insurance territory. The last one is typically covered by your equipment warranty.
Warranty vs. Insurance: Don’t Confuse the Two
This is the biggest misunderstanding among solar owners in India.
- Warranty covers manufacturing defects and underperformance — a panel degrading faster than promised, or an inverter failing due to a factory fault. It comes free from your manufacturer or installer.
- Insurance covers external, unpredictable events — fire, lightning, storms, floods, theft, and accidental damage. It’s a policy you pay for annually.
In short: warranty protects you from the manufacturer’s mistakes. Insurance protects you from the world’s mistakes. You genuinely need both.
What Does Solar Insurance Cover?
A good policy protects your entire system — not just the panels:
- Solar panels/modules
- Inverter and charge controllers
- Battery storage (if installed)
- Mounting structures, wiring, and connectors
And it typically covers these risks:
- Fire, lightning, and explosion
- Storms, cyclones, hail, and floods
- Theft and burglary (cable-only theft is usually excluded)
- Accidental damage — falling branches, construction mishaps
- Inverter breakdown, in comprehensive plans
What it won’t cover: normal wear and tear, gradual degradation, manufacturing defects, or damage from poor installation. Those remain the responsibility of your warranty and installer.
How to Get Covered
- Home Insurance Add-On — The simplest and cheapest option for most residential owners. Your solar system is added as a rider to your existing home policy, treated like any other permanent fixture. Works well for systems up to about 10 kW.
Important: most home policies don’t automatically cover solar panels just because they’re installed. You need to formally declare the system to your insurer and get it added to your policy schedule in writing otherwise a claim can get rejected later.
- Standalone Solar Policy — A dedicated policy independent of home insurance, better suited for commercial systems, larger residential installations, or anyone who wants clearly defined coverage rather than relying on how a home policy interprets “fixtures.”
- All-Risk Cover with Breakdown — Adds accidental damage and inverter/equipment breakdown on top of standard fire-and-theft cover. Useful for larger homes and small commercial setups, though it can overlap with a strong inverter warranty so check your warranty terms before paying extra for this.
What Does It Cost?
System Size |
Approx. Annual Cost |
| 3 kW | ₹1,500 – ₹2,500 |
| 5 kW | ₹2,500 – ₹3,500 |
| 10 kW | ₹5,000 – ₹7,000 |
| 20 kW+ / Commercial | 0.2% – 0.5% of system value |
Basic home-insurance add-ons can cost as little as ₹125–500 per year for smaller systems. Your premium will also depend on location states with higher storm or flood risk, like Odisha, West Bengal, Kerala, Gujarat, and Maharashtra, typically see 30–35% higher premiums than lower-risk states like Rajasthan or Punjab.
Who Offers Solar Insurance in India
The Ministry of New and Renewable Energy (MNRE) recognises six insurers with specialised solar products:
- New India Assurance – New India Solar Energy Insurance Policy
- HDFC ERGO – Solar Panel Warranty Insurance, also offers a home-insurance add-on
- ICICI Lombard – Photovoltaic Panel Warranty Insurance
- Tata AIG – Weather Insurance Policy and Solar Module Warranty Insurance
- IFFCO-Tokio – Photovoltaic Sales Policy
- Cholamandalam MS – Chola Solar Plant Protect
For most residential customers, the simplest path is to call your existing home insurer and ask them to add your solar system to your policy.
A Quick Note on the PM Surya Ghar Subsidy
The central subsidy (up to ₹78,000) covers only the capital cost of installation not ongoing insurance. Since it protects a subsidised asset you’ve already invested in, it’s worth budgeting for separately.
Do You Actually Need It? A Quick Check
- Already have home insurance? Just get your solar system formally declared you may already be covered for fire, storm, and theft.
- Live in a storm-prone, flood-prone, or theft-prone area? Consider dedicated or standalone cover.
- Have a long, full-replacement inverter warranty? You likely don’t need breakdown add-ons let insurance focus on external risks only.
Our Recommendation
- Declare your system with your home insurer, in writing don’t assume it’s automatically covered.
- Keep your paperwork ready invoices, serial numbers, and installation certificate. Claims move faster when this is in order.
- Match your cover to your actual risk go standalone or all-risk if you’re in a high-exposure area or have a larger system.
A solar system is a 20–25 year investment. A small annual premium to protect it against fire, theft, and weather isn’t an extra expense it’s simply good sense.
Contact Us
Chirayu Power Pvt. Ltd.
Head Office / Factory: C-1/1, M.I.D.C., Near Law College, Khamgaon – 444303 (Dist. Buldhana, Maharashtra)
Sales Offices: Mumbai (Thane), Pune, Nagpur
Call: +91 9112114440 | +91 7721871188
Email: sales@chirayupower.com | purchase@chirayupower.com
Website: chirayupower.com
Have questions about protecting your Chirayu Power solar installation? Reach out to our team we’ll help you find the right coverage for your system.
FAQs
Is solar insurance compulsory in India?
No, but it’s strongly recommended to protect against fire, storms, and theft.
Does my home insurance already cover my solar panels?
Only if you’ve declared the system in writing and it’s permanently fixed to your roof.
What’s the difference between insurance and warranty?
Warranty covers manufacturing defects, free from the manufacturer. Insurance covers external events like fire and storms, at an annual premium. You need both.
How much does solar insurance cost?
Around ₹125–800/year as a home add-on, or 0.2%–0.5% of system value for standalone policies.
Does it cover inverter failure?
Only if caused by an external event like a lightning surge — normal failure is a warranty matter.
What’s not covered?
Wear and tear, degradation, manufacturing defects, and poor installation damage.
Which insurers offer it?
MNRE recognises New India Assurance, HDFC ERGO, ICICI Lombard, Tata AIG, IFFCO-Tokio, and Cholamandalam MS.